Federal Retirement Match Estimator
Enter your estimated annual basic pay and desired TSP contribution percentage to see exactly how much free money the government adds to your account.
Tip: Contribute at least 5% to maximize the match.
Your Contribution
$0
Gov't Auto + Match
$0
Total Annual Addition
$0
Note: This calculation includes the mandatory 1% Automatic Agency Contribution plus the matching formula (100% match on first 3%, 50% match on next 2%). It does not include Social Security or FERS Annuity accruals.
Why contribute 5%? The government stops matching after you contribute 5% of your pay. Contributing less than 5% means you are leaving part of the "free money" on the table. Contributing more than 5% is great for savings but doesn't increase the government's match percentage.
You are staring at a job posting for a federal position. The salary looks decent, but your mind races to the one question that decides if you take the leap: do government jobs match 401K? If you are coming from the private sector, where employer matching is often the golden carrot of compensation packages, this uncertainty can feel like walking into a dark room. Here is the short answer: No, federal employees do not have a 401(k). But before you panic, understand that they have something arguably better: the Thrift Savings Plan (TSP) with automatic contributions and matching.
The confusion stems from terminology. A 401(k) is a specific type of defined-contribution plan used by private companies. Government employees, specifically those under the Federal Employees Retirement System (FERS), participate in the TSP. While the names differ, the mechanics of saving for retirement are similar enough that understanding one helps you grasp the other. However, the contribution rules, matching formulas, and fee structures are distinct. Let’s break down exactly how federal retirement savings work so you can compare apples to apples-or rather, TSPs to 401(k)s-without getting burned by assumptions.
The Core Difference: TSP vs. 401(k)
To understand if the benefits "match," you first need to know what you are actually signing up for. A 401(k) is a qualified retirement plan sponsored by an employer, allowing employees to contribute pre-tax income. The key feature most people hunt for is the employer match. For example, many private firms offer a 50% match on the first 6% you contribute.
Thrift Savings Plan (TSP) is a defined-contribution retirement plan for U.S. federal employees and uniformed services members, administered by the Federal Retirement Thrift Investment Board. It functions similarly to a 401(k) but comes with unique advantages, primarily extremely low fees and a limited selection of high-quality investment funds. Unlike a typical 401(k), which might charge 0.5% to 1.5% in administrative fees depending on the provider, TSP fees hover around 0.04%. Over a 30-year career, that difference compounds into tens of thousands of dollars.
So, while there is no 401(k) match because there is no 401(k), there is a TSP match. And for many federal employees, this match is superior to what they received in the private sector.
How the Federal Matching Formula Works
If you are worried about missing out on free money, rest easy. The federal government does provide matching contributions, but the formula is structured differently than the standard "dollar-for-dollar up to X%" model you might be used to. Under FERS, the agency automatically contributes 1% of your basic pay to your TSP account every year, regardless of whether you contribute anything yourself. This is known as the Automatic Contribution.
Beyond that automatic 1%, the government matches your own contributions using a specific formula:
- Dollar-for-Dollar: The government matches 100% of your contributions for the first 3% of your salary.
- 50-Cent Match: The government matches 50 cents for every dollar you contribute between 3% and 5% of your salary.
- No Match Above 5%: Contributions above 5% of your salary receive no additional matching funds.
This means the maximum effective match rate is 5% of your salary. To get the full benefit, you must contribute at least 5% of your pay. If you contribute less, you leave free money on the table. If you contribute more, you are simply investing your own money without extra help from the agency. Compare this to some private sector plans that cap matches at 3% or 4%, and you can see why federal employees often consider this a competitive advantage.
FERS Annuity: The Hidden Third Pillar
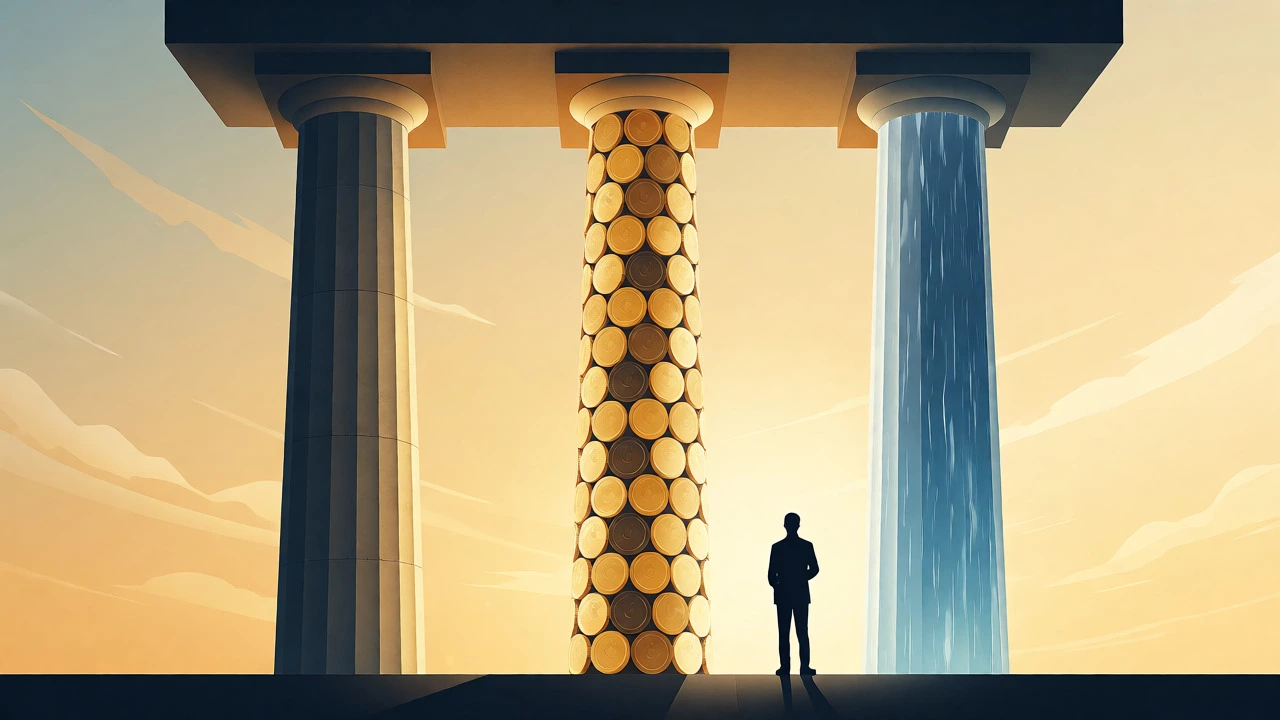
When comparing government jobs to private sector roles, focusing solely on the TSP misses half the picture. Private sector employees rely almost entirely on their 401(k) balance to fund retirement. If the market crashes right when you retire, your income drops. Federal employees have a third pillar: the FERS Annuity.
The Federal Employees Retirement System (FERS) is a three-tier retirement program consisting of a Basic Benefit Plan, Social Security, and the Thrift Savings Plan. The Basic Benefit Plan provides a guaranteed monthly pension based on your years of service and highest average salary. This annuity is funded by mandatory payroll deductions (currently 4.4% of gross pay for most new hires) and agency contributions. You don’t choose to opt-in; it’s part of the package.
While the TSP is variable and subject to market risk, the FERS annuity is predictable. In 2026, a federal employee retiring after 30 years with a High-3 average salary of $100,000 would receive approximately $3,000 per month from the annuity alone, plus whatever they saved in their TSP and earned from Social Security. Private sector workers rarely have this guaranteed income stream unless they worked for legacy companies with defined-benefit pensions, which are now rare.
Fee Structures and Investment Options
One area where government jobs consistently outperform private sector equivalents is cost efficiency. Many 401(k) plans include expensive mutual funds or proprietary company stock options with high expense ratios. The TSP offers only five core funds, all index-based and incredibly cheap.
| Feature | Typical Private 401(k) | Federal TSP |
|---|---|---|
| Average Expense Ratio | 0.50% - 1.20% | 0.04% |
| Investment Choices | Dozens to Hundreds | 5 Core Funds + Lifecycle |
| Employer Match Cap | Varies widely (often 3-6%) | Up to 5% (plus 1% auto) |
| Loan Availability | Common | Available (with restrictions) |
| Rollover Flexibility | High | High (to IRAs or other govts) |
The low fees mean more of your money stays invested. If you invest $10,000 annually for 30 years with a 7% return, a 1% higher fee could cost you over $100,000 in final balance. The TSP’s simplicity forces discipline-you can’t gamble on obscure hedge funds-but it also protects you from predatory financial products common in corporate plans.
Who Should Choose Which?
Deciding between a private sector role with a 401(k) and a government job with a TSP depends on your risk tolerance and long-term goals. If you value flexibility and aggressive growth, a private sector job with a high-matching 401(k) and access to diverse investment options might appeal. However, if you prioritize stability, low costs, and guaranteed income, the federal package is hard to beat.
Consider the "Total Compensation" view. A private sector job might offer a higher base salary, say $90,000 versus $80,000 in government. But once you factor in the FERS annuity, the automatic 1% TSP contribution, the 5% match, lower healthcare premiums, and generous leave policies, the gap narrows significantly. Furthermore, government jobs often provide better work-life balance, reducing the hidden costs of burnout and turnover.
There is also the portability factor. Can you move your 401(k) easily? Yes. Can you move your TSP? Also yes. Both allow rollovers to IRAs or new employer plans. However, keeping your money in the TSP even after leaving government service is often wise due to its low fees. You can keep contributing to your IRA, but you cannot contribute to a TSP once you leave federal service unless you return within a specific window.
Strategic Tips for New Federal Employees
If you land a government job, here is how to maximize your retirement strategy immediately:
- Contribute at Least 5%: Never contribute less than 5% of your pay to the TSP. Anything below that means you are forfeiting the partial match on the 3%-5% band.
- Utilize Roth TSP: If you expect your tax bracket to be higher in retirement, contribute to the Roth TSP. Contributions are made after-tax, but withdrawals in retirement are tax-free. This diversifies your tax exposure.
- Don’t Ignore the L-Funds: The Lifecycle (L) funds are target-date funds that automatically adjust asset allocation as you age. They are set-and-forget investments ideal for those who don’t want to manage portfolios actively.
- Check Your Agency’s Leave Policy: While not a direct retirement benefit, the ability to use annual leave strategically affects your final High-3 salary calculation. Maximizing leave usage before retirement can sometimes impact your pension payout timing.
Remember, the goal isn't just to find a job that "matches" a 401(k). It's to build a retirement portfolio that aligns with your life. For millions of Americans, the federal system offers a robust, low-cost, and secure path to financial independence that rivals-and often exceeds-what the private sector provides.
Can I roll over my old 401(k) into the TSP?
Yes, you can roll over eligible assets from a previous employer's 401(k) plan into your TSP account. This allows you to consolidate your retirement savings and potentially take advantage of the TSP's lower fees. Ensure the funds are transferred directly to avoid tax penalties.
What happens to my TSP if I quit the government?
You have several options: you can leave the money in the TSP, roll it over to an IRA, transfer it to a new employer's plan, or withdraw it. Leaving it in the TSP is often recommended due to the low management fees, provided you are satisfied with the available investment choices.
Is the TSP match guaranteed?
The matching formula is established by law and applies to all FERS employees. However, the actual funding depends on congressional appropriations. Historically, the match has been consistent and reliable, making it a dependable component of federal compensation.
Do I still pay Social Security taxes in a government job?
Yes, most modern federal employees hired after 1984 pay into Social Security. This means you will receive Social Security benefits upon retirement, adding another layer to your income alongside the FERS annuity and TSP savings.
What is the current contribution limit for the TSP?
For 2026, the IRS sets the annual elective deferral limit for TSP contributions, which typically mirrors the 401(k) limits (e.g., around $23,000-$24,000 for those under 50). Always check the latest IRS guidelines for exact figures as they adjust annually for inflation.